AS FEATURED ON
 Featured on CNA Money MindTop 3% of financial servicesCertified Financial Planner (CFP®)
Portfolio Optimisation · Structured Retirement Planning
You’ve built real wealth.
The real question is whether your current setup can sustain your lifestyle for the next thirty years.
Six questions · One minute · No income questions
Built alongside
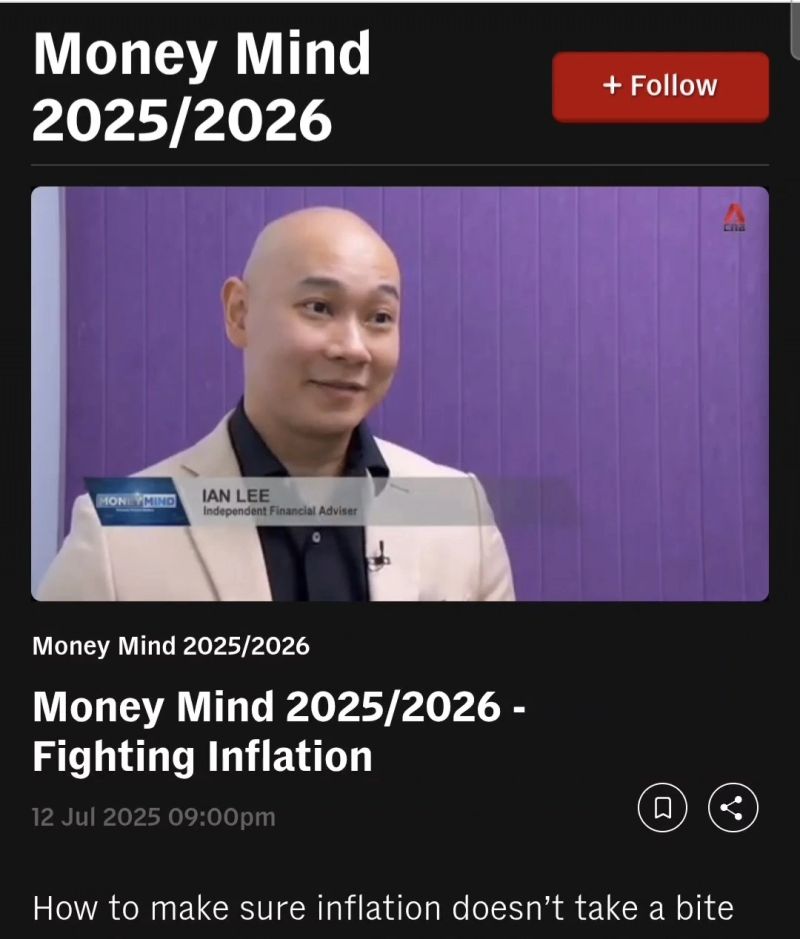
Ian Lee has been interviewed twice on CNA Money Mind: on fighting inflation in retirement, and on why tax-free is not always better. He sits in the top 3% of financial services and works with high net worth families to structure their capital for retirement income.
Why this matters now
At the level you’re at, most of your capital is already exposed. In equities, property, or positions built to grow.
That served you during accumulation. It doesn’t serve you now.
Drawing down requires a different structure. A portion of your capital positioned defensively, paying you monthly.
We help you make that shift, focusing on risk management, and on objective advice.
The same money. A different job to do.
We restructure your existing capital, where appropriate and subject to your individual circumstances, so it generates monthly income efficiently, without you needing to trade, monitor markets, or chase returns.
The strategies we use are designed to support your income goals of $10,000+ while prioritising capital preservation and risk management. Peace of mind is the point.
If doing nothing is the right answer, we say so. We start with your goals, then build the plan around them.
Your lifestyle stays funded during your lifetime. The capital still gets to your beneficiaries afterward.
Six questions · One minute · No income questions
The framework
Most people hold the pieces already. What they don’t have is the pieces working together.
Four income sources, mapped against the lifestyle you actually want to fund.
Your retirement income, layer by layer
Each layer pays what it pays. The cost of the lifestyle keeps rising. Where the stack stops short of the line is the gap the review is built to find.
Swipe the chart sideways to see every year →
Illustration only, with rounded example figures. Not a projection, not advice. Your own layers are mapped in the session.
We will not walk you through the method here. That is what the session is for.
Who this is for
Across cash, deposits and portfolios. You are exploring structured approaches to manage it.
You may have experienced losses in the past, and prefer regulated solutions over speculative strategies.
You would rather have a structure that works than a portfolio that needs you.
You are considering how to sustain retirement income while balancing risk.
You wish to preserve capital for the next generation through structured planning.
Introduction
You will be matched with whichever of them fits your situation better.
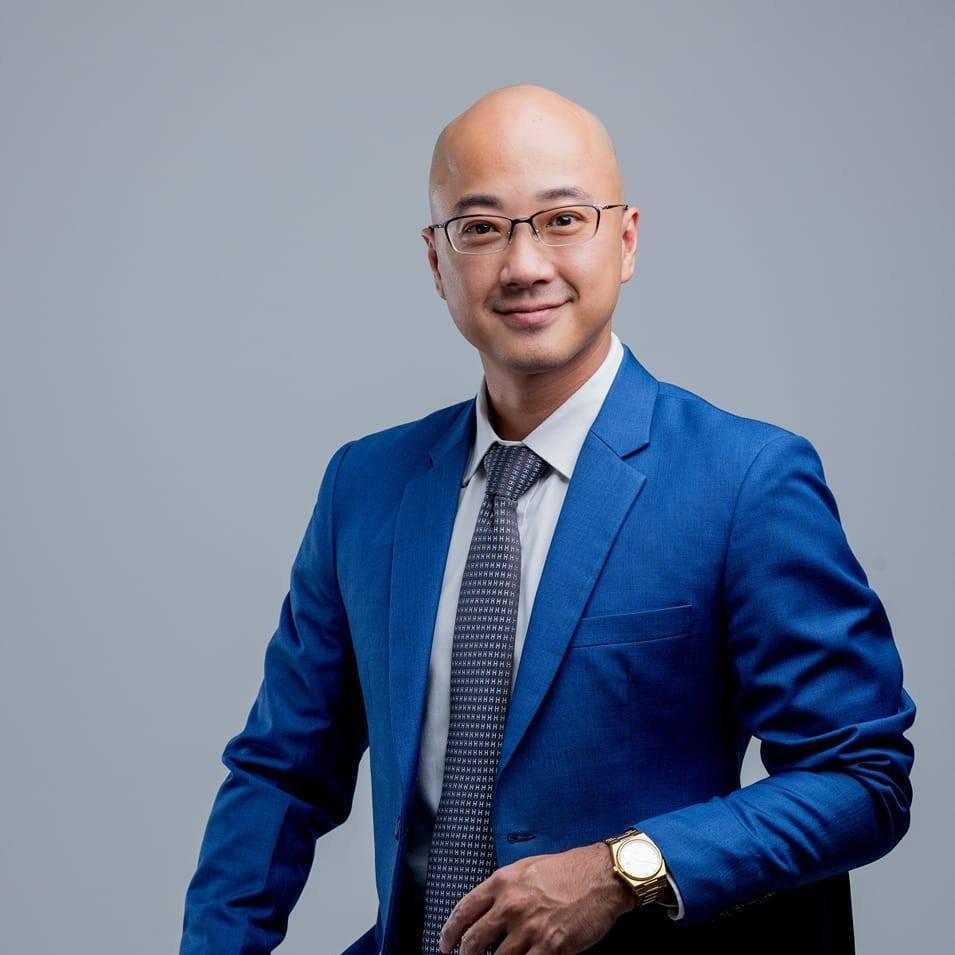
“My grandparents owned land. Without a plan, it all crumbled away. That is why I do this.”
David has spent 15 years helping successful Singaporeans turn what they have already built into income they can actually live on.
He is a Certified Financial Planner, and sits in the top 3% of financial services.
His work covers both halves of the problem. Structuring your capital to pay you through retirement, and making sure what is left passes cleanly to the people you leave it to.
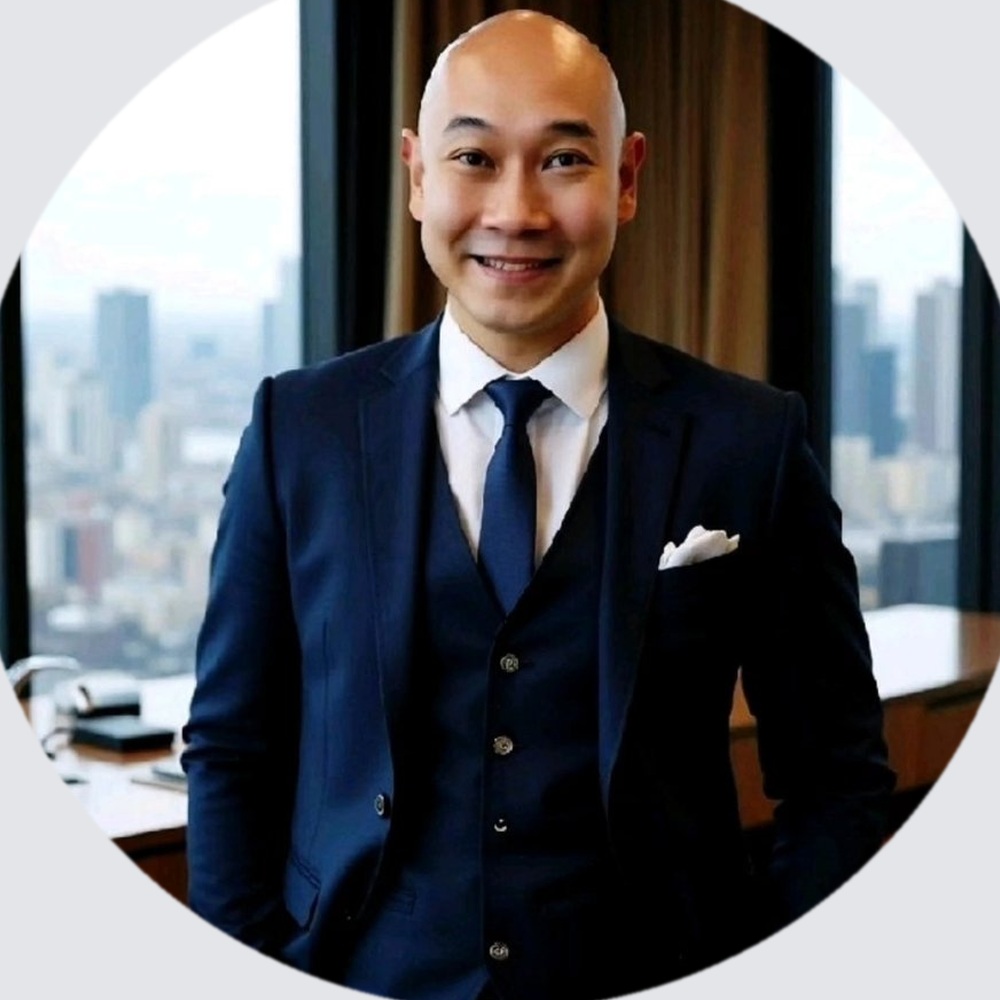
“Most people do not have a returns problem. They have a structure problem.”
Ian works with families who have built real wealth and now need it to produce income they can rely on.
He sits in the top 3% of financial services.
Interviewed twice on CNA Money Mind: on fighting inflation in retirement, and on why tax-free is not always better. His focus is the structure underneath the number.
Six questions · One minute · No income questions
In their own words
 ★★★★★
He listened patiently to my needs and helped me with investment strategies that are important to my retirement planning. Everything was explained to me in detail, patiently, with no hard selling. I now have more confidence in my retirement through investments that preserve my capital and generate a reliable passive income.
We live in a four-room flat. Most people assume we are comfortable. Ian was the first advisor who realised we were actually wealthy, and treated us accordingly.
 ★★★★★
Even as a trained investment professional who is familiar with various financial products myself, David continues to bring valuable insights to my financial planning. I highly value his honesty and realistic approach.
I was spending too much time managing my own portfolio. The review freed me from that. Now I enjoy the work I want to do and ignore the rest.
 ★★★★★
David was able to help me plan my retirement, giving me very good advice. I like his honesty in giving what is best for his clients instead of for himself. I am blessed to have him as my financial planner.
What struck me was the quietness of the conversation. No pressure. No product pitch. Just someone mature enough to listen before they prescribe.
Six questions · One minute · No income questions
In just one minute, answer six questions and get an indication of whether your current wealth is structured to sustain your lifestyle.
Start my 1-minute assessment →Confidential · No obligation · Senior-advisor only
Your 60-minute private review is with David or Ian.